Introduction
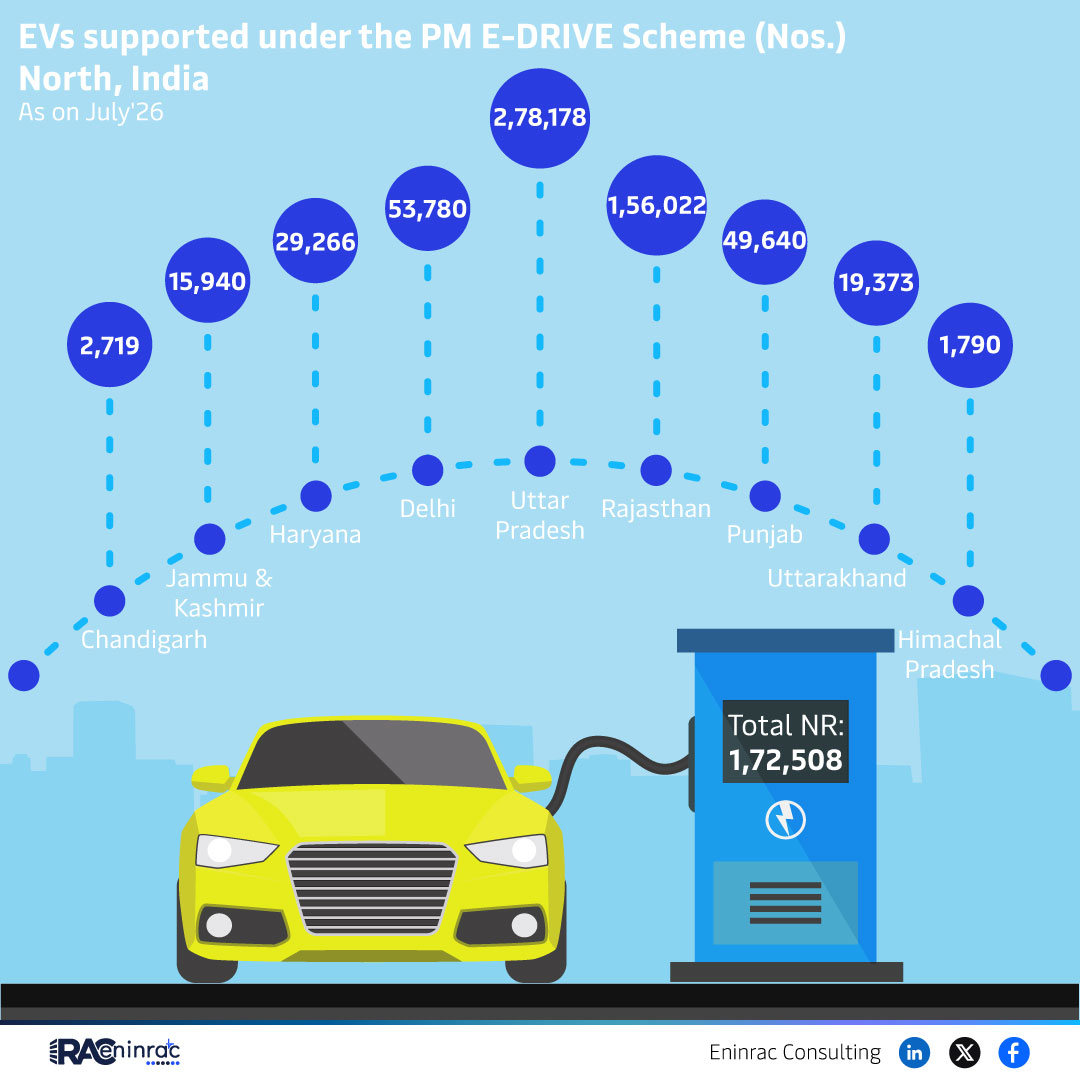
Renewable energy statistics are essential for understanding the pace of the global transition to clean power. The latest dataset records 78,178 individual projects and a cumulative total of 172,508 units, reflecting rapid expansion across multiple regions. This article breaks down what these numbers mean, why they matter to investors and policymakers, and how they shape future market dynamics. You will also discover regional patterns, sector impacts, and practical insights for strategic decision‑making.
What Does the Data Reveal About This Topic?
The data reveals that renewable energy development remains robust, with over seventy‑eight thousand projects contributing to more than one hundred seventy‑two thousand units in total. This indicates a strong pipeline of installations and suggests that market confidence is high despite variable policy environments. The sheer volume also highlights the diversification of project types, from solar farms to wind parks, across both emerging and mature markets. Moreover, the growth trajectory points to increased financing activity and technology adoption worldwide.
Regional Distribution of Renewable Projects
When examining the geographic spread, Asia leads with the highest share of the 78,178 projects, followed closely by Europe and North America. In Asia, China alone accounts for roughly 30 % of the total units, while India and Japan contribute significant volumes as well. Europe’s strength lies in distributed solar and offshore wind installations, and North America shows steady growth in utility‑scale solar farms and hybrid projects. These regional patterns underline where capital is flowing, where policy incentives are most effective, and where future capacity additions are likely to concentrate.
Impact on Sectors and Industries
The surge in renewable project numbers directly influences several key sectors. Energy utilities are expanding their generation portfolios, while equipment manufacturers see heightened demand for turbines, panels, and storage solutions. Financial institutions are launching green bonds and sustainability funds to capitalize on the robust pipeline. Policymakers gain clearer benchmarks for setting targets, and communities benefit from cleaner air and job creation. The data therefore serves as a catalyst for coordinated investment and regulatory action across the entire clean‑energy ecosystem, driving innovation and economic growth.
Key Takeaways
- 78,178 renewable projects indicate rapid global expansion.
- 172,508 total units reflect substantial capacity growth.
- Asia dominates project count, with China contributing ~30% of units.
- Europe and North America show strong diversification in solar and wind.
- Increased projects boost demand for clean‑tech equipment and financing.
- Data provides benchmarks for policymakers and investors alike.
FAQs
What types of renewable projects are included in the dataset?
The dataset covers solar farms, on‑shore and offshore wind parks, hydroelectric facilities, battery storage installations, and emerging technologies such as geothermal and green hydrogen projects.
Which region has the highest number of projects?
Asia leads the count, driven primarily by China, India, and Japan, which together host the majority of the 78,178 recorded projects.
How does the increase in projects affect investors?
More projects expand investment opportunities, improve portfolio diversification, and enhance risk‑adjusted returns for funds focused on clean energy and sustainability mandates.
What role do governments play in supporting this growth?
Governments provide subsidies, tax incentives, and renewable‑target mandates that encourage project development, reduce financing costs, and accelerate market adoption.
How can businesses use these statistics for strategic planning?
Businesses can align product development, supply‑chain investments, and market entry strategies with the identified growth regions, technology trends, and capacity forecasts revealed by the data.